
Albert Instant
 Written by Kenji Niwa
Albert Instant is an unsecured line of credit issued by FinWise Bank, with limits from $25 to $1,000, though few people qualify for the full $1,000. Each draw can carry a draw fee, which Albert shows in the app before you confirm, and late fees may apply if you miss your due date. Albert does not pull your credit report, but it does use data from consumer reporting agencies. No Albert subscription is required. Albert's disclosures also list a separate Instant Advance, offered at Albert's discretion, with no interest or late fees.
$1,000
Max advance
Draw fee on each draw, based on the amount. Albert doesn't publish the schedule; the fee is shown in the app before you confirm.
Subscription
None
Credit check
The details
- Max advance
- Up to $1,000
- Limit resets
- Other
- Mandatory fees
- Draw fee on each draw, based on the amount. Albert doesn't publish the schedule; the fee is shown in the app before you confirm.
- Premium plan (optional)
- $19.99/mo to $39.99/mo, optional and not required for Albert Instant
- Interest
- Not published (draw fees apply)
- Late fee
- May apply (amount not published)
- Credit check
- None
- Direct deposit required?
- No
- Bank-link required
- Yes (Linked bank account and debit card)
- Instant transfer
- Instant, to your Albert Cash account
- Tips
- None
- Eligibility
- Limits range from $25 to $1,000, and few people qualify for $1,000. Albert sets your limit from your linked bank account activity, your transaction history, and information from consumer reporting agencies. A linked debit card is required. Not offered in Colorado, Connecticut, Iowa, Maine, Minnesota, Montana, Nevada, New Jersey, South Dakota, Vermont, or Wisconsin. If you repay more than 15 days late, draws may be suspended for 30 days or more, and more than 30 days late, for 90 days or more.
Pros & cons
Pros
- You can draw up to 6 times in a 30-day period.
- No Albert subscription is required.
- Draws land in your Albert Cash account instantly.
Cons
- Albert doesn't publish its draw fees. You only see the fee in the app before you confirm.
- Late fees may apply, and repaying late can suspend your access for 30 days or more.
- Few people qualify for the full $1,000, and it isn't offered in every state.
Compare Albert Instant to other cash advance apps
Albert Instant
—- Max advance
- $1,000
- Instant fee
- —
- Monthly fee
- Varies
- Max advance
- $1,000
- Instant fee
- Not published
- Monthly fee
- $0
- Max advance
- $750
- Instant fee
- $3.99–$37.49
- Monthly fee
- $0
- Max advance
- $500
- Instant fee
- $4.49 to $14.99
- Monthly fee
- $5.99/mo
After this app, similar apps from the same list are picked automatically: apps from Firstcard partners first, then the rest, each group by Firstcard editors' rating. That order may reflect partner compensation, as how we rate explains. It never changes a rating. The full list shows them all. Clicks are Firstcard members sent to each app in the last 12 months, with suspected bot traffic excluded.
A warning from Firstcard
- Borrow with a plan. Take an advance only for a specific, necessary expense, and know exactly which paycheck repays it before you tap the button.
- Don't stack apps. Using more than two cash advance apps at once is how the debt spiral starts. We don't recommend it, ever.
- Avoid instant fees. Express delivery is extremely expensive for the days it saves, see the APR math above. If a free delivery option exists, use it.
Relying on an advance every paycheck? Learn how these apps really work →
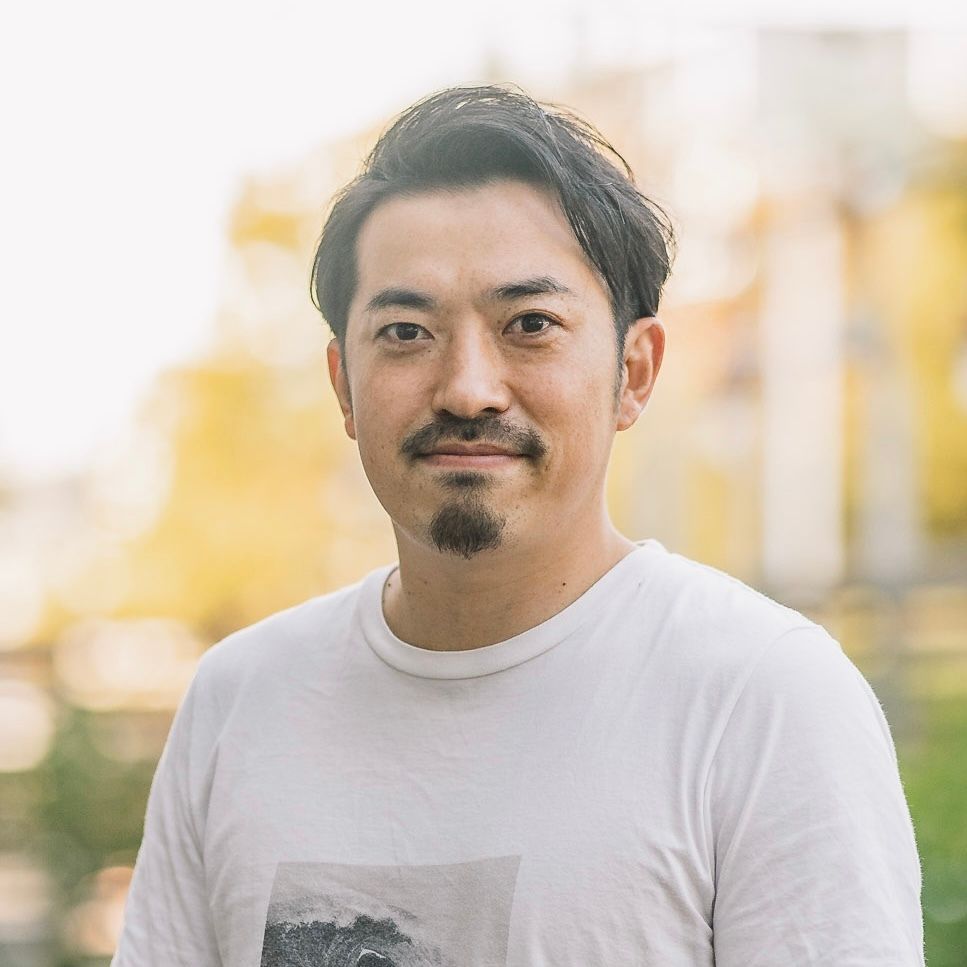
Kenji is the Founder and CEO of Firstcard. He built and sold iTank, Japan's largest internship platform, and has made about 40 angel investments, including Substack. He started Firstcard at UC Berkeley Haas after he was rejected for his first U.S. credit card. Full profile and latest articles →

How Firstcard works
Firstcard exists to make finance simple and accessible, so anyone can choose the right financial product with confidence. That means showing every fee and every catch upfront, and holding ourselves to the same standard. Here is how Firstcard works, and how we make money.
How we rate. Our editors' rating for a cash advance app weighs what it truly costs to use (the instant fee plus any required subscription, not the advertised “no interest”), how much you can actually get, how fast the free option delivers, what you need to qualify, and how repayment works. Ratings run 1 to 5 in tenths and compare products only within their own category, so a 4.5-star cash advance app is not “better” than a 4.0-star credit builder: they do different jobs. Treat the rating as one input, not the decision. See how we rate financial products.
How we make money. Firstcard may earn a commission when you click a link on this page, get approved, or open an account. That is what keeps our comparisons free to use. See how we make money and our current partners.
Ratings versus placement. Star ratings, member reviews, and our cost math are never influenced by money, and no partner sees a review before it publishes. Where a product appears is a separate question: featured spots and default ordering can reflect partner compensation and what members click and choose. That is why the rating and the real numbers travel with every product, wherever it sits. See our Advertiser Disclosure and Editorial Guidelines.
Terms change, so check before you apply. These terms come from the providers, not from us, so we cannot guarantee they are current or complete, and anything a member reports describes their own account rather than the offer you will be given. Always confirm the fees and terms on the provider's own site before you apply. If you spot something wrong here, email support@firstcard.app and we will fix it.


